A carrier approves a new commercial auto program. It has the license and the policy paper. It does not have the local agency network, or the staff to review hundreds of small fleet submissions each month. So it gives underwriting authority to an outside firm. That firm quotes, binds, and issues policies on the carrier’s paper.
That firm is a managing general agent, or MGA. If you searched for what is an mga insurance, this is the short answer. The rest of this guide explains how the arrangement works, where the risks sit, and what carriers and MGAs should check.
What is an MGA in insurance?
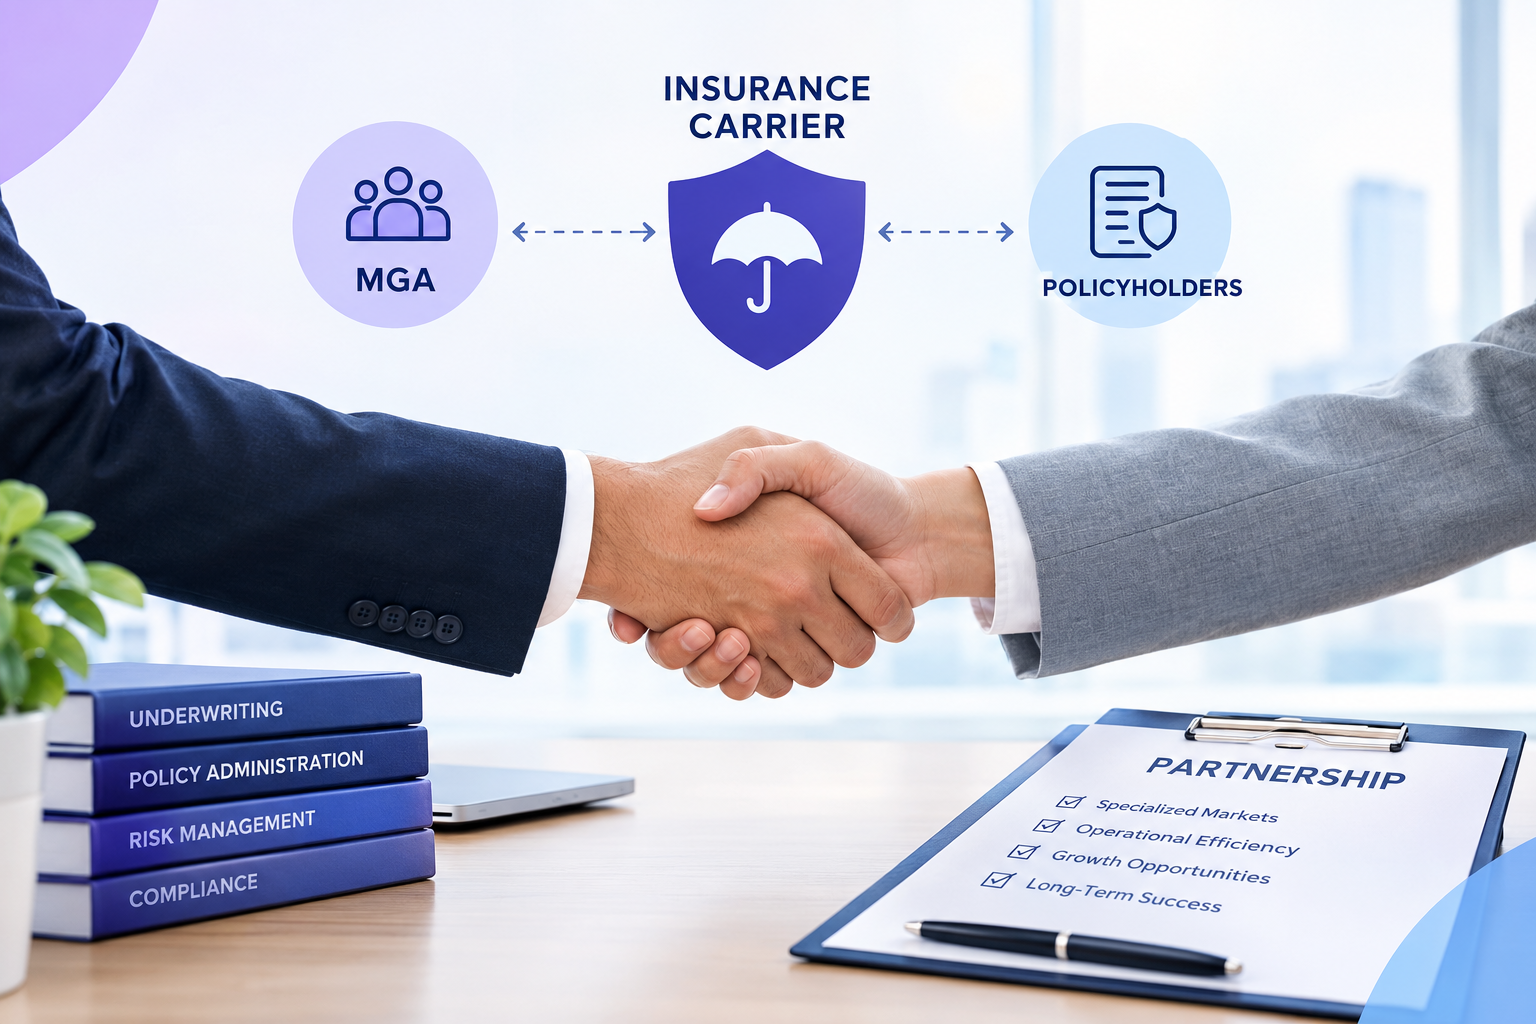
An MGA is a firm that holds delegated authority from one or more insurance carriers. That authority usually covers underwriting, binding coverage, and issuing policies. Some MGAs also handle claims.
The Insurance Risk Management Institute (IRMI) describes an MGA as a type of agent or broker that, unlike a traditional one, holds underwriting authority from an insurer.
The NAIC’s state licensing handbook uses similar language. It describes an MGA as an insurance producer that an insurer authorizes to manage all or part of its business.
The key point: the MGA is not the insurer. The carrier still carries the risk on its balance sheet. It sets the guidelines, approves the program, and reviews the results.
How MGAs work with carriers
The MGA and the carrier work under a written agreement, usually called a program agreement or MGA contract. It sets out what the MGA can do and what the carrier expects in return. Most agreements cover these areas:
- Authority: The types of insurance the MGA can write, the states it can operate in, and the coverage limits it can offer.
- Guidelines: The underwriting rules, acceptable pricing ranges, and cases that need the carrier’s approval.
- Money: How premiums are collected and passed to the carrier, along with how commissions are paid.
- Claims: Whether the MGA handles claims itself or works with a third-party administrator (TPA).
- Reporting: What premium, loss, and exposure data the MGA must share with the carrier and how often.
- Audits: When the carrier can review policy files and how those reviews are carried out.
Here is how responsibility usually splits:
| Task | Carrier | MGA |
| Holds the license and policy paper | Yes | No |
| Sets underwriting guidelines | Approves them | Works within them |
| Quotes, binds, and issues policies | Grants authority | Performs the work |
| Carries the loss exposure | Yes | Usually no, unless the contract shares risk |
| Reports results | Receives reports | Prepares and sends reports |
MGA vs. retail agent vs. broker
People mix these terms up. The differences come down to authority and who the firm works for.
| Feature | Retail agent or broker | MGA |
| Underwriting authority | Usually none | Delegated by the carrier |
| Policy issuance | Places business with carriers | Issues policies on carrier paper |
| Main job | Sells and places coverage | Builds and runs a specialty program |
| Carrier relationship | Appointed to sell the carrier’s products | Contracted to act for the carrier |
A traditional agent usually represents the insurer. A broker usually represents the buyer. An MGA sits in a different spot. It acts for the carrier in underwriting decisions, even though it may also work with agents and brokers to place the business.
Why MGAs are growing
The MGA channel has grown fast in the US. Insurance Journal reported, citing Conning, that direct premiums written by U.S. managing general agents topped $114 billion in 2024.
AM Best measured a different total with its own method. It found that premium written through MGAs and other delegated underwriting authority enterprises rose 15% to $89.9 billion in 2024, the fourth straight year of double-digit growth.
The totals differ because the two studies count premium differently. Both point the same way: MGA premium is growing faster than the wider property and casualty market.
Fronting also plays a big role. Fronting companies are licensed carriers that issue policies for MGAs without taking the full risk. Conning’s 2023 analysis estimated that fronting companies accounted for more than $14 billion in premium written by MGAs that year.
Regulation: what carriers and MGAs must track
MGAs are regulated mostly at the state level. The NAIC has adopted the Managing General Agents Act to guide states, but each state decides how to apply it. Many states regulate the activities and contracts of MGAs.
Here is an example. The Kansas Insurance Department requires insurers to notify the state commissioner in writing within 30 days of signing or ending a contract with an MGA.
Your compliance team should check the rules in every state where the MGA writes business. Rules change, and a missed filing can take months to fix.
What an MGA does day to day
The daily work usually includes:
- Reviewing submissions against the carrier’s guidelines
- Referring edge cases to the carrier’s underwriters
- Quoting and binding coverage
- Issuing policies and endorsements on carrier forms
- Collecting premium and tracking what is owed to the carrier
- Handling or overseeing claims, depending on the contract
- Sending reports and loss data back to the carrier
Each step creates paperwork. Each file has to match the guidelines. That is where the operational load builds up.
Where MGAs feel operational pressure
Most MGAs begin with a small team where everyone knows the files and what is happening with each case. As business picks up, keeping up with the paperwork gets harder. Common problems include:
- Too much time goes into checking underwriting files
- Endorsements pile up waiting to be processed
- Claims paperwork does not get reviewed on time
- Premium collections and records stop matching
- The team spends days getting monthly reports ready
The workload grows with the program, but much of it does not need the MGA’s underwriting expertise. Many MGAs keep handling these tasks internally until volume becomes hard to manage.
Techsurance is an insurance KPO company that helps carriers, MGAs, and TPAs with underwriting file preparation and review, along with claims documentation. The MGA still makes the final decisions and keeps its authority, while the support team handles the preliminary checks.
Key risks for carriers and MGAs
| Risk | What it looks like | Common control |
| Authority creep | MGA writes outside approved classes | Clear guidelines and referral triggers |
| Loss surprises | Results show up months late | Monthly loss reporting and reserve reviews |
| Weak documentation | Files fail audit | Maker-checker review on each file |
| Inconsistent claims | Similar claims get different outcomes | Written claims authority and QC sampling |
| Compliance gaps | State filings missed | Calendar of state requirements, owned by one person |
Metrics carriers track with MGAs
Carriers usually watch these numbers closely:
- Loss ratio: losses paid and reserved, divided by earned premium
- Expense ratio: operating costs, divided by written premium
- Combined ratio: loss ratio plus expense ratio. Under 100% means an underwriting profit.
- Bind-to-issue time: how long a policy takes to move from bind to issued paper
- Referral rate: how often the MGA sends files to the carrier for review
- Audit exception rate: how many sampled files have errors
How to evaluate an MGA partner
If you are a carrier choosing an MGA, ask for the following before you sign:
- Active licenses in each target state
- Written underwriting guidelines and referral rules
- Sample files and a pilot period with full review
- Reporting cadence and the format of loss data
- Claims authority, and who approves payments
- Errors and omissions insurance and financial stability
- Audit rights and data security controls
Read the contract carefully. The exact authority, termination terms, and profit-sharing language decide how the arrangement works when things go wrong.
Conclusion
An MGA has the authority to quote, bind, and often issue policies on behalf of an insurance carrier. That authority comes from the carrier, which continues to take on the risk and decide the underwriting rules. For carriers, it is a way to reach specialty markets. For MGAs, it means they can expand without setting up their own paper.
The relationship depends heavily on what the contract says, how clear the underwriting guidelines are, and how well reporting is managed. It is worth sorting these out early. When files start piling up, claim documents get delayed, or reporting becomes hard to manage, insurance outsourcing can help with the workload. Talk to Techsurance about using an insurance KPO team for the checks, so your underwriters can stay focused on the decisions.
FAQs
Is an MGA an insurance company?
No, an MGA does not act as the insurer itself. It handles certain responsibilities for an insurance company under a written agreement. The carrier is still the one with the license, the policies issued in its name, and the financial risk if claims come in.
How does an MGA make money?
Most MGAs earn commission on the premium they produce. Some also earn fees or profit-sharing. The contract sets the split, so check the terms before you agree to them.
What is the difference between an MGA and an MGU?
The terms overlap. Both usually refer to firms with delegated underwriting authority. The label depends on the contract and the state. Read the agreement to see what authority the firm really has.
Who regulates MGAs?
States do. Many states regulate the activities and contracts of MGAs, and the NAIC provides model guidance. Each state can apply that guidance differently, so check the rules in every state where the MGA writes business.
Can an MGA work with more than one carrier?
Yes. Many MGAs hold agreements with several carriers. Each carrier sets its own guidelines, so the MGA has to manage different rules for each program.
What does an MGA need to get started?
It usually needs producer licenses in each target state, a written agreement with at least one carrier, and systems for underwriting, billing, and reporting. Carriers also expect proper errors and omissions coverage and clear claims procedures.
When should an MGA consider KPO support?
When file volume grows faster than the team can review it, or when checks start to slow binding. A KPO team can handle the document checks and back-office tasks. The MGA’s underwriters keep the final decisions.
