An underwriter asks for five years of loss runs on a commercial account. The broker has the policy numbers, and the insured is cooperative. What’s missing is the claims history itself. Until the loss runs arrive, the submission sits idle.
Waiting on loss runs is a common reason commercial placements get delayed. Getting them is usually not difficult, but you need to know who to contact at each carrier, what to ask for, and how long the request may take. This guide covers how to get loss runs from insurance carriers, what the reports contain, and what to do when a carrier is slow to respond.
What Are Loss Runs?
Loss runs are reports of claims filed under an insurance policy over a set period. For each claim, you’ll usually find the date of loss, the current status, and the amount the insurer has paid or reserved.
Carriers produce these reports, and no single format is standard. Some show a count of open and closed claims. Others include a few lines describing what happened.
Underwriters review loss runs to gauge the risk of insuring a business. A history with fewer claims may support lower rates. Frequent claims can mean higher premiums or a refusal to offer coverage. Brokers need these reports to prepare submissions, and business owners often keep copies for their own records.
Who Can Request Loss Runs?
Usually, one of three parties can make the request: the named insured, a producing broker or agent with authorization, or the insured’s prior agent in some cases.
Many carriers require a signed letter of authorization from the insured before they release loss runs to a third party. Check each carrier’s rule before you send the request. A missing signature is one of the most common reasons a request gets rejected.
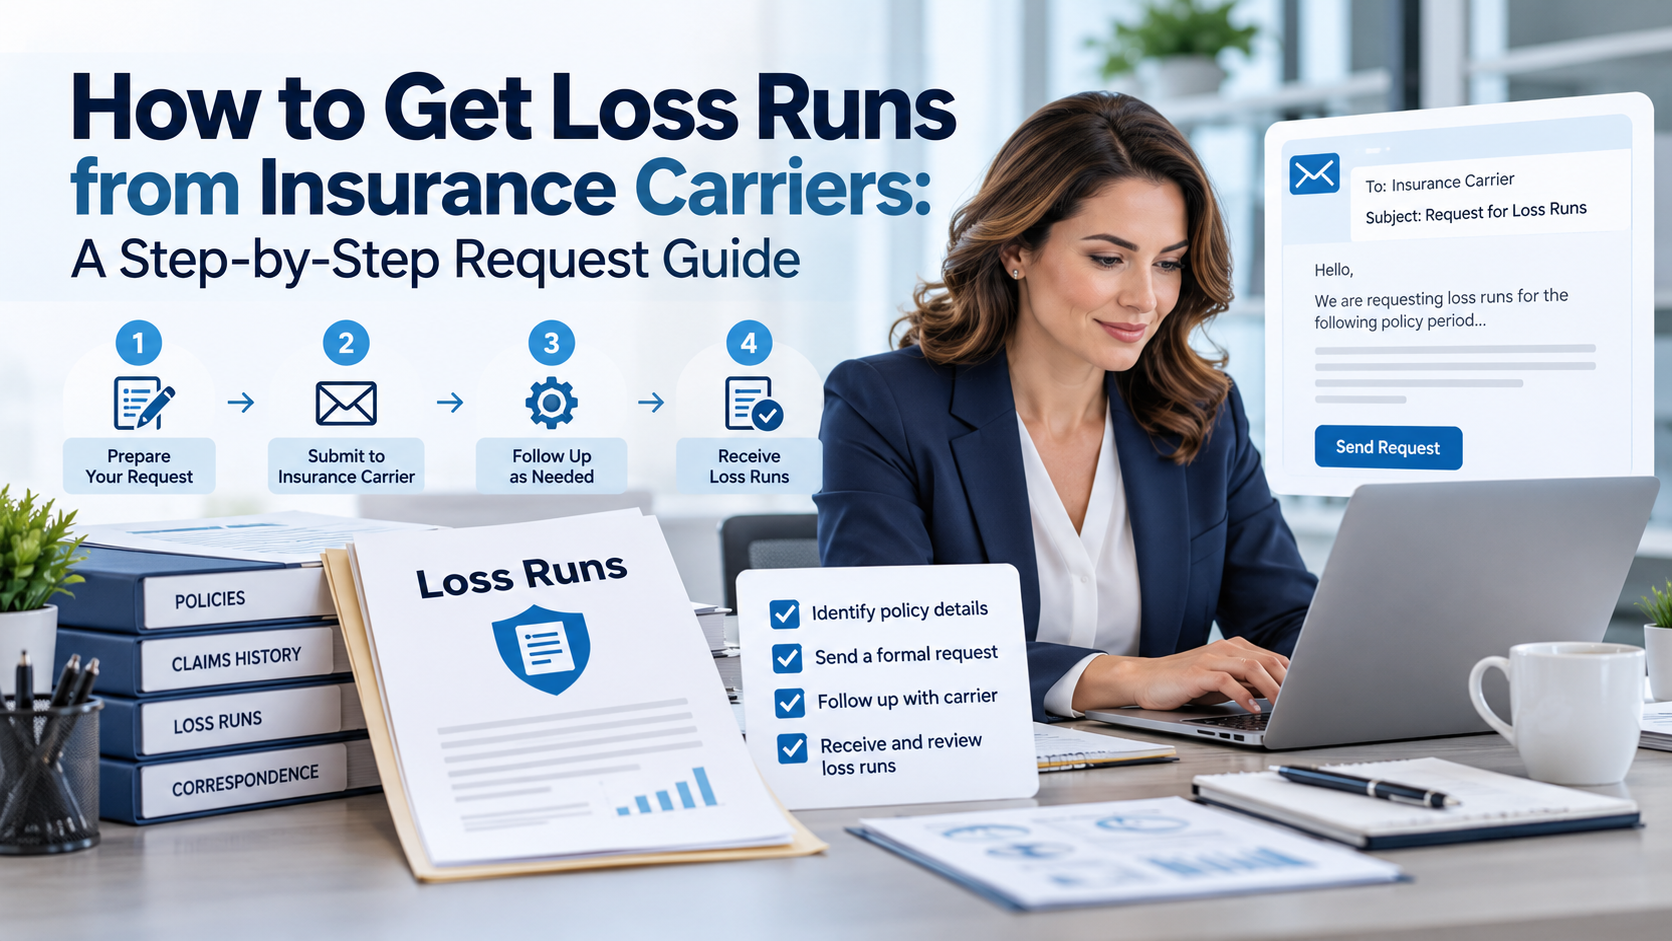
The Request Process: Step by Step
Step 1: Build a Carrier and Policy List
Start with a simple table. Include the carrier name, policy number, policy period, and line of business.
If the insured changed insurers, list every carrier for the review period. A business that switched carriers has two or more sets of loss runs to collect.
Gaps cause problems. If one policy period is missing, the underwriter will ask again, and the clock starts over.
Step 2: Confirm the Right Contact at Each Carrier
Depending on the carrier, loss run requests may go to the claims department, a policy service team, or a dedicated loss run unit. Some carriers accept email. Others still require a portal submission or a fax.
Check the carrier’s current process before you send anything. A quick call or a look at its website can confirm where the request should go. Don’t assume contact details from a previous placement still work.
Step 3: Prepare the Request Letter
A written request keeps the file clean and makes follow-up easier. A complete loss run request letter includes:
- Named insured and mailing address
- Policy number and policy period for each request
- Carrier name and the department receiving the request
- Your name, agency name, and contact details
- Signed authorization from the insured, if required
- The format you need, such as currently valued loss runs
- Delivery method and destination
Send a separate request to each carrier. Individual letters are easier to track than a combined request that has to be sorted out later.
Sample Loss Run Request Letter
Subject: Loss Runs for [Insured Name], Policy [Number], [Period]
Dear [Carrier] Loss Run Department,
Could you please send us the latest valued loss runs for [Insured Name], policy [Number], covering [start date] through [end date]?
I’ve attached the signed authorization from the insured.
You can send the report to [email] or use [preferred delivery method]. If you need any other information, please reach me at [phone] or [email].
Thank you,
[Name]
[Title]
[Agency]
Step 4: Ask for Currently Valued Loss Runs
A loss run is only useful if it reflects recent claim activity. Ask for currently valued loss runs, which show a valuation date and the claim status as of that date.
Without a valuation date, an underwriter may treat old figures as current. That can lead to the file being questioned or returned.
Step 5: Track Every Request
Record the date you sent each request, the carrier, the delivery method, and the reply date the carrier gave you.
If that date passes without a response, follow up with the carrier. Some take longer than expected, and a delay doesn’t always mean the request was lost.
How Long Does It Take to Get Loss Runs?
Timing depends on the carrier, the line of business, claim volume, and whether the request is complete. Some carriers respond within days. Others take longer, especially when a request is missing a signature or uses the wrong format.
Ask each carrier how long its reports usually take before you submit. Build that time into your submission schedule. If the deadline is close and some reports are still missing, send what you have and tell the underwriter what’s outstanding. Whether they’ll review the file in the meantime depends on the underwriter, so ask before you send it.
Waiting until the last week before renewal is a common cause of delay. Start early.
When a Carrier Is Slow or Refuses
Work through this checklist before you escalate:
- Confirm the request reached the right department.
- Make sure the authorization is signed and dated.
- Check the policy number and coverage period against the carrier’s records.
- Find out whether the carrier needs a different format or valuation date.
- If time is short, call instead of sending another email.
If a carrier still refuses or stalls, tell the underwriter in writing. Ask whether they’ll accept a pending item or whether they need the loss runs before they can quote.
Currently Valued Loss Runs: What Underwriters Expect
Date requirements vary. Depending on the carrier and the type of insurance, reports may need to be valued within 30, 60, or 90 days of the application.
| Valuation window | What it means for your request | Practical action |
| Within 30 days | Strictest window | Order loss runs one to two weeks before you need them |
| Within 60 days | Common for many commercial lines | Confirm the carrier’s standard, then plan the request date |
| Within 90 days | More flexible for some carriers | Check whether it applies to your line before relying on it |
Confirm the required window with the underwriter before you order. A report valued too early may need a new request, and that costs time you may not have.
Common Mistakes That Slow Down Loss Run Requests
- Using the same request letter for every carrier
- Leaving out a policy period, especially after a carrier change
- Not including the signed authorization
- Sending the request to an outdated contact or fax number
- Requesting loss runs without checking the valuation date
- Not following up when reports haven’t arrived within the expected time
- Waiting until renewal is near to request the reports
Manual Requests Versus an Organized Process
| Area | Manual process | Organized process |
| Carrier contacts | Looked up per request, often outdated | Kept in one list and checked regularly |
| Request letters | Written from scratch each time | Standard template with policy details filled in |
| Tracking | Email threads and memory | Log with dates, status, and follow-up dates |
| Quality check | Depends on the person | Checklist applied before submission |
| Volume handling | Slows during renewal peaks | Scales through a defined workflow |
Teams handling many accounts benefit from a fixed workflow, particularly in the weeks before renewal season.
How Techsurance Can Help
Loss run collection is one step in a larger submission process. Underwriting teams often need help with the work around it, including file preparation and document checks before a submission goes out.
Techsurance supports carriers, MGAs, and TPAs with underwriting support from case receipt to policy issuance, claims processing, and other operational services, including policy administration and back-office work. If your team needs help with document-heavy submission work, contact our team to discuss the scope.
Conclusion
Getting loss runs is not complicated, but the details matter. Identify each carrier, send a complete request letter, confirm the reports have recent valuation dates, follow up on anything outstanding, and check each report before it goes into the file. Start ahead of renewal. A missing signature or an old valuation date can slow the whole process.
FAQs
How long does it take to get loss runs from insurance carriers?
Each carrier has its own processing time, which also depends on whether the request includes every required detail. Ask the carrier about its usual timing and send your request well before the submission deadline.
What is a currently valued loss run?
It is a loss run that shows claim status as of a recent valuation date. Underwriters often require one that falls within a set window before the application date.
Do I need the insured’s permission to request loss runs?
Many carriers require a signed authorization from the insured before they release loss runs to a third party. Confirm each carrier’s rule before you send the request.
What should a loss run request letter include?
The letter should show the insured’s name, policy numbers, coverage dates, and the carrier’s name and department. Add your contact information, any authorization the carrier requires, and how you want the records delivered.
What if a carrier does not respond?
Contact the carrier again by phone or email. Confirm you’ve reached the right department and that the request is complete. If the delay could affect a deadline, tell the underwriter you’re still waiting on the records.
What if the business is new and has no loss runs?
A business with no prior coverage may not have loss runs to provide. Ask the underwriter what they’ll accept in their place before the submission goes out.
