Insurance operations are under pressure from every side. Carriers face rising claim volumes, longer underwriting queues, higher staffing costs, more stringent regulatory review, and growing expectations for service speed. At the same time, insurers lack access to trained talent with the domain expertise needed to run operations smoothly.
A commonly used solution that insurers use to manage this constraint is outsourcing to KPO service providers, often benefiting from between 40 and 60% lower costs when they outsource as well. However, outsourcing operations involves a thorough understanding of cost implications, risk factors, and SLAs that guarantee outcomes. This article compares in-house and outsourced insurance operations across cost, risk, SLA performance, scalability, and long-term operating value.
What are in-house insurance operations?
In-house insurance operations refer to internal teams that manage the day-to-day work required to keep an insurance business running. Structurally, insurance businesses run in-house operations via different structures depending on the size and scale of the business, but they typically cover the same areas:
| In-house function | What the internal team handles | Common pressure point |
| Underwriting assistance | Submissions, data review, quote inputs, file indexing, and renewal files | Backlogs during high-volume periods |
| Claims processing | Claim documents, status updates, payment records, and file checks | Longer cycle times during surges |
| Policy servicing | Endorsements, renewals, cancellations, reinstatements, and documents | Errors during busy renewal windows |
| Quality review | File checks, process checks, and exception review | Limited reviewer capacity |
| Audit preparation | File collection, documentation checks, and review packs | Heavy workload near audit dates |
| Regulatory documentation | Required records, logs, and process checks | Variation across states or products |
What is insurance operations outsourcing?
Insurance operations outsourcing means assigning selected insurance workflows to a specialized external partner. The purpose is to help internal teams manage their workload while maintaining process control and service standards. Here’s how outsourcing works in various insurance operational functions:
- Underwriting assistance: External teams can review submissions, validate data, index files, prepare quote inputs, manage APS workflows, and assist with renewals. This gives underwriters more time for risk decisions.
- Claims processing: Teams can review claim documents, check file completeness, assist with reserve validation inputs, flag fraud indicators, and prepare files for quality review. This helps claims teams move files forward.
- Policy servicing: Operations teams can handle endorsements, renewals, reinstatements, cancellations, policy issuance tasks, and document processing. This keeps service queues moving during peak periods.
- Quality review: Specialized teams can review files against SOPs, client rules, documentation standards, and state process requirements. This reduces rework.
- Audit preparation: Teams can gather files, check records, prepare review packs, and organize audit trails. This helps internal teams respond faster.
- Regulatory documentation: External teams can maintain logs, status reports, filing records, and process checks to support internal and external reviews.
In-house vs outsourced insurance operations comparison
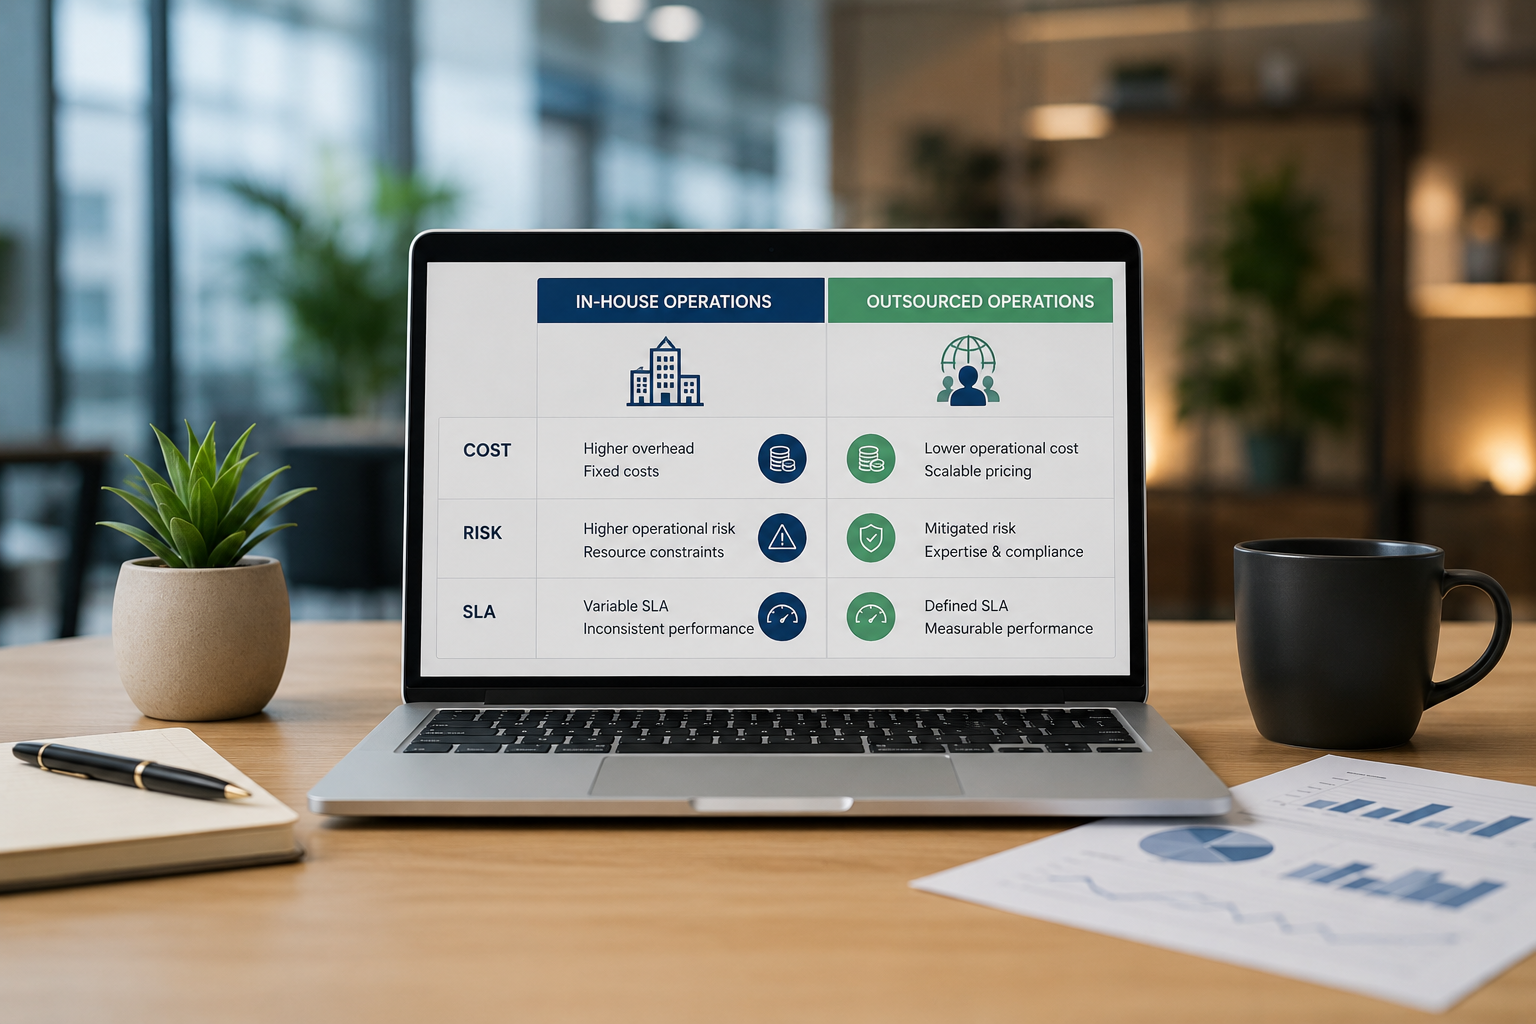
A common starting point in the in-house vs outsourced decision revolves around costs. However, a well-rounded decision considers other variables such as capacity, risks, SLA performance, service quality, use of technology, and ability to cope with varying operational demands. Here’s how both models fare across key operating areas:
| Area | In-house operations | Outsourced insurance operations |
| Hiring and training costs | High due to recruitment, onboarding, and ongoing training | Lower operating overhead through externally trained teams |
| Scalability | Slow when hiring pipelines are long | Flexible capacity across peak and steady volumes |
| SLA management | Depends on staffing levels and internal queue size | SLA-based workflows with defined tracking |
| Turnaround time | Can vary during peak periods | Managed through workflow plans and capacity balancing |
| Regulatory monitoring | Internal team carries the full burden | Dedicated quality and regulatory review assistance |
| Peak volume handling | Challenging during claims spikes or renewal seasons | Faster workforce expansion through trained pools |
| Rework rates | Higher when the quality review capacity is limited | Lower through layered file review |
| Operational visibility | Direct control through internal systems | KPI and SLA dashboards through partner reporting |
| Expertise availability | Depends on hiring and retention | Insurance-trained teams available across functions |
| Cost predictability | Variable due to overtime, attrition, and idle capacity | More planned through a defined service scope |
| Responsiveness to change | Typically more responsive to changes as stakeholders are predominantly internal | Limited by SLAs and can often require multiple rounds of discussion before pivoting processes |
| Data security | Holding customer data in-house generally reduces the risk of exposure | While outsourcing partners who have data security frameworks in place are reliable, outsourcing certainly presents a data security risk as customer/company data gets handled by third-party employees. |
Cost comparison: Hidden operational costs most insurers miss
Many insurance leaders start the cost comparison by looking at salaries. However, that gives only a partial view. Internal operations also incur other costs, such as recruitment, training, management, technology, quality review overhead, rework, overtime, attrition, and idle time. To get a complete understanding, it is important to consider all these costs. Here’s a complete list of costs that often get missed, as well as how outsourced models provide insurance businesses with a competitive advantage:
| Cost area | In-house cost driver | Outsourced model advantage |
| Recruitment | Job ads, recruiter fees, interviews, and hiring delays | Partner manages staffing pipeline |
| Training | Time spent training staff on systems, products, and workflows | Insurance-trained teams can ramp faster |
| Attrition | Replacement hiring and loss of process knowledge | Partner absorbs team turnover planning |
| Quality review | Internal managers spend time checking files | Built-in quality review can be part of the delivery |
| Rework | Errors require extra staff time and delayed completion | A layered review reduces repeated corrections |
| Overtime | Peak periods drive extra payroll costs | Flexible capacity handles spikes |
| Idle capacity | Low-volume periods leave staff underused | Scaled service scope can match workload |
| Technology | Workflow tools, licenses, dashboards, and reporting | The partner can bring process tracking tools |
Risk and regulatory control comparison
Insurers often believe that outsourcing will introduce risk into the business. However, in reality, risk arises from a variety of factors, including non-standardized workflows, poor documentation, and insufficient review, which can also occur in in-house operations. A specialized partner can actually reduce risk by providing trained teams, secure systems, file checks, and documented SOPs. Here are some controls that strong outsourcing partners should have built into delivery:
- Cross-file consistency checks: Reviewers compare similar file types to catch variation in handling. This helps reduce uneven work quality across teams.
- Final logic reviews: A reviewer checks whether the file makes sense before it is completed. This helps catch missing dates, incomplete fields, or unusual entries.
- Peak-period quality review: Extra file checks during volume spikes help maintain quality as queues rise.
- Risk escalation workflows: Teams route exceptions, unusual claims, missing records, or state-rule concerns to the appropriate internal owner.
- Documentation checks: Reviewers check notes, file history, attachments, and required fields before delivery.
- Data handling protocols: Approved access, system rules, and user activity tracking protect sensitive insurance records.
The real risk is often rework, not outsourcing
Many insurers worry that outsourcing increases risk. The larger risk often comes from rework. Rework can occur in an in-house or outsourced model when files move too quickly, lack quality checks, or omit required information.
Rework creates several problems. It slows turnaround time. It increases the cost per file. It creates extra touches for staff. It can delay claims or policy changes. It can also create avoidable loss when errors affect billing, claims, or policy records.
A specialized insurance operations partner can reduce this by checking required fields before underwriter review, flagging gaps early, and tracking missing data through a defined workflow.
The same applies to claims. A claim file without required documents can move through several queues before anyone notices the gap. A partner with staged review can identify the missing item earlier and shorten the cycle.
SLA performance and turnaround time
SLA performance is one of the strongest reasons insurers evaluate outsourcing. In-house teams can meet SLAs when capacity matches volume. The challenge appears when capacity gets stretched. That’s where outsourced operations provide an advantage. Here’s how SLA driven outsourced operations can improve major insurance workflows:
| Workflow | SLA challenge in in-house models | How outsourced operations help |
| Underwriting turnaround | Submissions wait for data checks and file setup | Teams validate data and prepare files faster |
| Claims cycle time | Documents wait for review and indexing | Teams review, organize, and route files |
| Endorsement processing | Requests pile up during renewal periods | Teams process standard changes through defined steps |
| Policy issuance | Missing documents slow completion | Teams check requirements before issuance |
| Backlog reduction | Internal staff handle too many queues | Partner capacity reduces aging work |
| Quality review | Managers review only a sample | Layered checks expand review coverage |
Which insurance functions are commonly outsourced?
Insurers outsource many functions when work volume increases or internal teams need more time to make complex decisions. Here are some of the most commonly outsourced insurance functions:
Underwriting assistance
Underwriting teams need complete, organized, and reliable files before making decisions. Outsourcing can help prepare files faster and reduce manual workload for underwriters. Tasks include:
- Submission intake
- APS management
- Data validation
- Quote preparation inputs
- File indexing
- Loss run review assistance
- Renewal file preparation
- Referral package preparation
Claims operations
Claims teams need speed and care. Outsourced teams can help move claim files through document handling, review, and status workflows. Tasks include:
- Document review
- Claim file indexing
- Claims quality review
- Settlement coordination assistance
- Fraud indicator flagging
- Reserve validation inputs
- Payment documentation checks
- Status update preparation
Policy servicing
Policy servicing affects customer records, coverage, billing, broker service, and renewal timing. Outsourced teams can help manage high-volume service requests. Tasks include:
- Endorsements
- Renewals
- Policy issuance tasks
- Cancellation processing
- Reinstatement processing
- Document processing
- Billing change assistance
- Broker request routing
Quality review and audit preparation
Quality review and audit preparation help insurers reduce rework and prepare for internal or external reviews. These tasks include:
- Audit readiness
- Documentation checks
- SOP adherence checks
- State process requirement assistance
- File sampling
- Exception reporting
- Cross-file consistency review
- Quality score tracking
Hybrid insurance operations models are growing
Many insurers now prefer a hybrid insurance operations model. This means core decision authority stays internal, while operational workflows move to a specialized partner. The table below shows how a hybrid model can divide work between internal teams and outsourced partners:
| Work area | Internal team role | Outsourced partner role |
| Underwriting | Risk decision, pricing, referrals, and authority management | Submission review, data validation, file indexing, and quote inputs |
| Claims | Claim decision, reserve judgment, settlement approval | Document review, file checks, status updates, quality review |
| Policy servicing | Exception handling and customer escalation | Standard endorsements, renewals, cancellations, and document work |
| Quality review | Quality strategy and review rules | File sampling, SOP checks, and issue reporting |
| Audit preparation | Audit response and final sign off | File collection, documentation checks, and review pack preparation |
| Reporting | Leadership review and business decisions | SLA dashboards, volume reports, and queue tracking |
How specialized insurance operations partners add value
Specialized insurance operations partners add value because they understand insurance workflows. They are different from generic vendors that only process tasks, bringing trained teams, defined procedures, quality review, SLA tracking, and experience across workflows.
Techsurance helps insurers with building process excellence across workflows, including underwriting, claims processing, hindsighting, and back-office operations. With a team of domain experts, backed by ISO-certified processes and technology to boost efficiency, Techsurance adds value to insurance operations, addressing the needs of insurers, including:
| Insurer need | Techsurance capability | Business value |
| Faster underwriting flow | Submission review, data validation, renewal assistance, and file preparation | Shorter queues and better underwriter productivity |
| Claims workload relief | Claim document review, file checks, and quality workflows | Faster claim movement and less internal strain |
| Policy servicing capacity | Endorsements, renewals, reinstatements, cancellations, and document processing | Better service consistency |
| Quality review | Layered file checks and SOP based review | Reduced rework and stronger file readiness |
| Audit preparation | Documentation checks, review packs, and process records | Faster review preparation |
| SLA management | Dashboards, queue tracking, and task aging reports | Better operating visibility |
| Scalable operations | Flexible teams for peak and steady work | More control over changing volume |
Conclusion
The in-house versus outsourced insurance operations decision is no longer a simple cost comparison. It is a strategic operating choice that affects cost, risk, SLAs, staff workload, file quality, and growth capacity. In house teams offer direct control and business familiarity. Outsourced insurance operations offer scalable capacity, SLA based workflows, layered review, and specialized insurance execution. Many insurers gain the strongest value through a hybrid model where internal teams keep decision authority and external teams handle repeatable, knowledge based work.
Techsurance offers insurance-trained teams, a quality-review approach, workflow tracking, and experience across underwriting assistance, claims processing, hindsighting, policy servicing, and back-office operations, helping insurers reduce rework, improve turnaround time, and manage changing volume with confidence. For carriers, MGAs, TPAs, brokers, and specialty insurers, specialized insurance operations outsourcing can create a stronger path to scale.
FAQs
What is insurance operations outsourcing?
Insurance operations outsourcing means assigning selected insurance workflows to a specialized external partner. These workflows can include underwriting assistance, claims processing, policy servicing, quality review, audit preparation, and regulatory documentation.
Is outsourcing insurance operations secure?
Outsourcing can be secure when the partner uses approved systems, controlled access, data handling rules, audit trails, staff training, and quality checks. Insurers should review security standards and process controls before selecting a partner.
Which insurance functions are commonly outsourced?
Common outsourced functions include submission review, data validation, APS management, claims document review, policy endorsements, renewals, cancellations, audit preparation, quality review, and bordereaux checks.
Does outsourcing reduce insurance operational costs?
Outsourcing can reduce operating costs by lowering recruitment pressure, training costs, overtime, rework, idle capacity, and management burden. The cost-benefit grows when workloads vary across seasons or product cycles.
How do SLAs work in insurance outsourcing?
SLAs define service expectations such as turnaround time, queue aging, quality scores, completion targets, and escalation timelines. A specialized partner tracks these measures through reports and dashboards.
How does outsourcing improve turnaround time?
Outsourcing improves turnaround time by adding trained capacity, splitting workflows into parallel tasks, tracking queues, managing escalations, and reducing rework. This helps underwriting, claims, and policy servicing tasks move faster.
